From Environmental to Financial risks: what European portfolios are already revealing
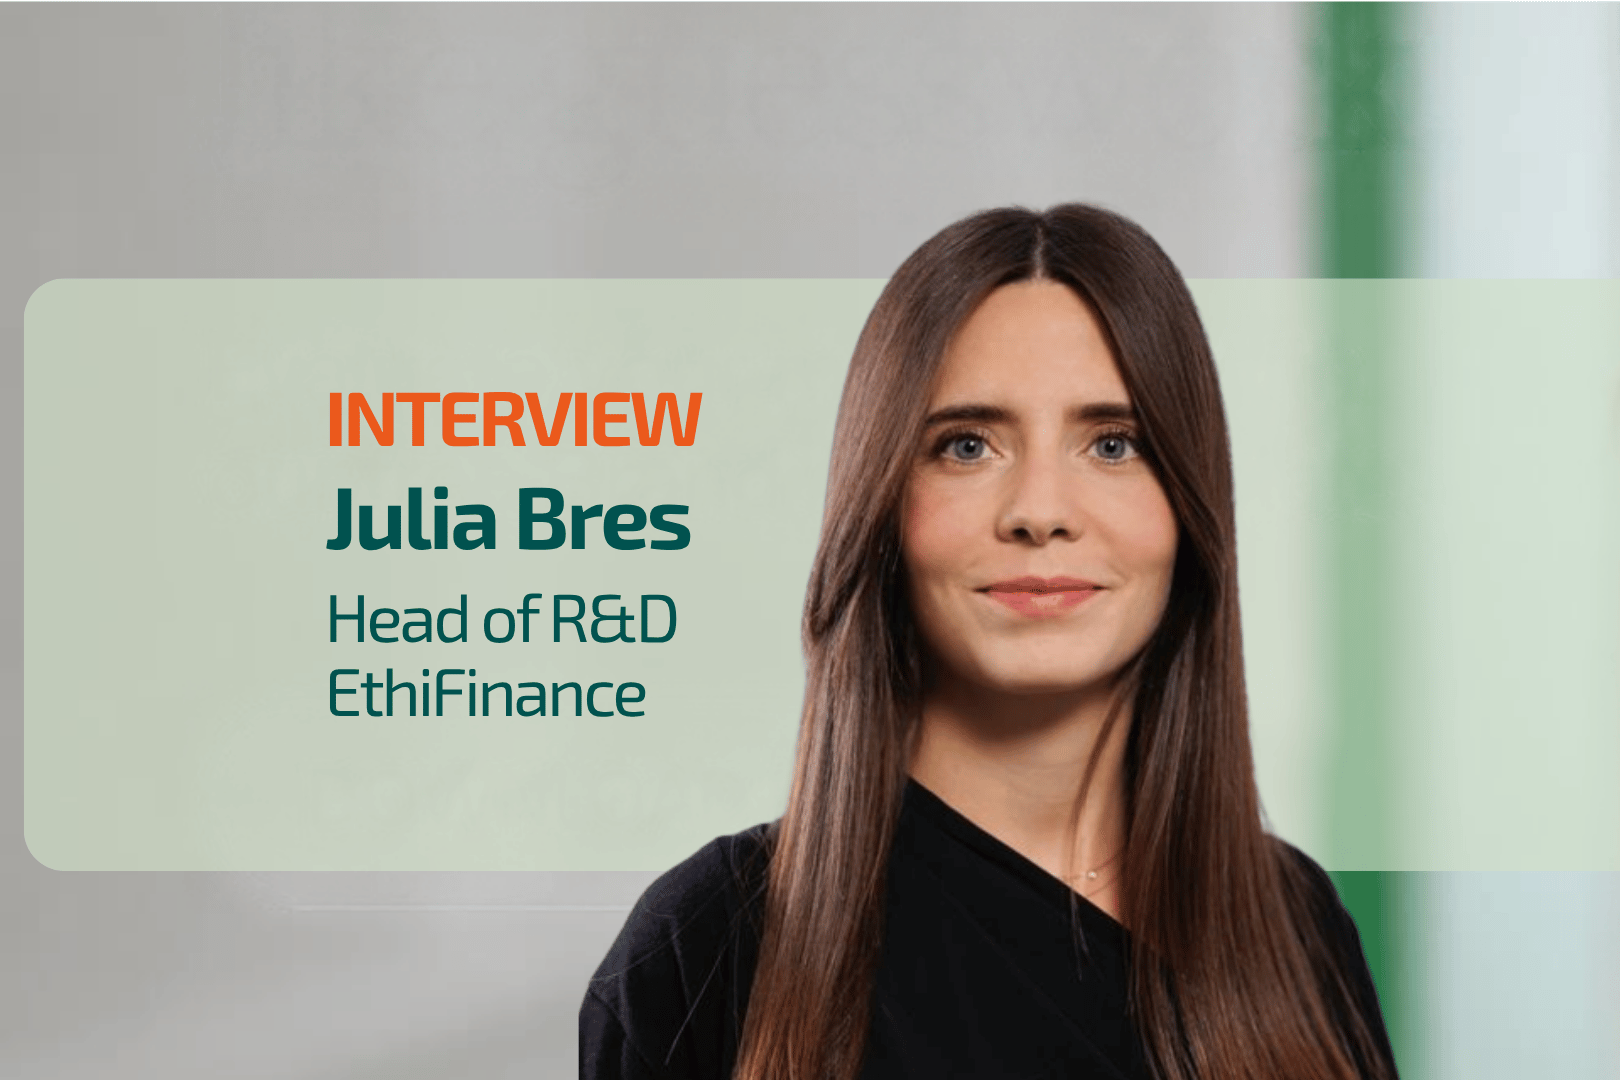
Interview with Julia Bres, Head of R&D at EthiFinance
Financial losses from environmental risks are already emerging across European portfolios, driven by chronic and acute climate hazards such as floods and wildfires, and by pressure on water resources and the degradation of species and habitats. Quantifying these losses remains more complex for biodiversity than for climate, because biodiversity has no single universal metric.
Julia Bres, Head of R&D at EthiFinance, and her team translate climate and nature data into financial risk indicators. Three main findings emerge from applications of the EthiFinance model: physical climate risks are already driving financial losses over the short and medium term; some more sustainable practices under optimistic scenarios can increase short-term pressure on water resources; but, in the longer term, a more sustainable pathway can significantly reduce the impacts of environmental risks.
What does your role at EthiFinance involve?
I lead EthiFinance’s R&D team, which brings together PhDs, research engineers, and data scientists. We bridge science and finance by translating climate, hydrological, and ecological projections into indicators that inform investment and financing decisions, combining them with economic and statistical models.
We develop our models directly with our investor and banking clients to ensure close alignment with their real-world needs. They cover both exposure to environmental risks and financial stress testing.
How do you assess the financial resilience of a portfolio?
At EthiFinance, we combine environmental metrics derived from scientific research with four company-specific factors: sector vulnerability, geographic exposure, the transmission of shocks through value chains, and financial health.
This enables us to estimate the potential financial losses of companies and their value chains under different forward-looking scenarios and time horizons. We have applied this approach with major French insurers, institutional investors and banks, as well as to French and Spanish stock market indices.
Which climate risks are most prominent in your financial impact analysis?
Physical risks, both chronic and acute, dominate our results. Recent wildfires, droughts, and heatwaves illustrate this.
Beyond risk scoring, our financial stress tests currently cover three hazards: floods, wildfires, and cyclones. Other climate hazards are currently assessed through scoring, with ongoing work to extend the approach to stress testing.
For the three hazards covered, both physical damage and estimated financial impacts increase over time. However, when scenarios are compared at the same time horizon, the estimated financial impacts are of a similar order of magnitude (Net Zero 2050, Current Policies or Fragmented World, following the NGFS scenarios[1]). The reason is climate inertia: between 2030 and 2050, we will experience the consequences of past emissions, regardless of the pathway followed today.
In the longer term, however, following a more sustainable pathway can significantly reduce the impacts of environmental risks compared with more pessimistic ones.
And what about biodiversity?
Water-related risks are significant at the European level, followed by risks related to species and habitats. Here, damage will increase over time.
One counterintuitive finding is that some more sustainable practices under optimistic scenarios can increase pressure on water resources in the short and medium term. For instance, sustainable agriculture can be more water-intensive, particularly in temperate countries like France, unlike the technology-driven models of pessimistic scenarios, as suggested by recent scientific publications [2],[3].
As a result, their financial impacts can be higher than under more pessimistic scenarios.
Which companies are best able to withstand the shock?
This depends first on the sector of activity and the upstream value chain. Unsurprisingly, the most vulnerable sectors consume natural resources and depend on the climate: extractive and manufacturing industries, transport and agriculture.
Financial health also matters. It determines a company’s ability to absorb a shock, change supplier, relocate assets, or innovate. Our study of the CAC 40 shows that the index resilience relies largely on a robust credit profile. For more exposed portfolios, with lower credit ratings or greater vulnerability through their supply chains, financial risks can become significant.
Can biodiversity-related risks now be quantified in a way that informs investment decisions?
This is more complex than for climate, for several reasons. Climate risks have been integrated into the regulatory framework for banks for several years. This is not yet the case for biodiversity, where assessment remains largely voluntary.
Climate also has an aggregable reference unit, greenhouse gas emissions expressed in CO₂ equivalent, linked to global warming pathways. Biodiversity is multidimensional and has no single universal metric.
Historically, regarding biodiversity, we have therefore focused more on scoring dependencies and impacts than on assessing financial risk. However, this is changing. In 2023, an ECB Occasional Paper[4] examined companies’ dependencies on ecosystem services, focusing on the state of species. In 2024, we broadened the approach to water, soils, the atmosphere, and habitats. For each, we identified a metric that tracks degradation across space and over time under different scenarios, and incorporated companies’ financial health. The ECB’s 2025 paper [5] then focused on water as a natural capital. This is a dimension we had already included in our methodology, and it confirms how critical this resource is.
Which methodological limitations still need to be addressed?
We still need a harmonized framework, with consistent metrics for each form of natural capital and compatible forward-looking scenarios.
We also need to improve how we model the way a dependency on ecosystem services translates into economic and financial loss. This is an area the NGFS is working on[6]. Company data also needs to be more granular, particularly on key assets, their locations, the natural resources they use and companies’ ability to cope with risk, and the adaptation measures already in place.
What key insights can be drawn from these analyses?
We are still consolidating the methodology, but we already have sufficient geosectoral and financial data to identify the most material risks, compare scenarios, and inform decision-making.
Across our European applications, the big picture is clear: acute physical risks and water-related risks emerge consistently. The next step is to collect more granular data to establish more realistic risk profiles.
To explore this topic further, take a look at our study "Biodiversity Stress Test: Assessing the resilience of the CAC 40 to the ecological crisis"
Biography of Julia Bres
After completing a PhD on modelling the interactions between climate change and vegetation at CEA, Julia Bres joined EthiFinance’s R&D team in 2023, driven by a desire to bridge academic research and real-world applications. Now Head of R&D, she develops methodologies to help financial institutions assess financial and extra-financial risks.
Notes
1. Network for Greening the Financial System [NGFS]. (2024). NGFS Climate Scenarios Technical Documentation (Phase V) (link).
2. Lemaitre-Basset, et al. (2024). Water use scenarios versus climate change: Investigating future water management of the French part of the Moselle. Journal of Hydrology: Regional Studies, 54, 101855.
3. Stenzel et al. (2021), “Irrigation of biomass plantations may globally increase water stress more than climate change”, Nature Communications.
4. Boldrini, S., Ceglar, A., Lelli, C., Parisi, L., & Heemskerk, I. (2023). Living in a world of disappearing nature: physical risk and the implications for financial stability (No. 333). ECB Occasional Paper. (link)
5. Ceglar, A., Jwaideh, M., O’Donnell, E., Danieli, F., Pasqua, C., Hutchinson, J., ... & Heemskerk, I. (2025). Nature at risk: Implications for the euro area economy and financial stability. ECB Occasional Paper, (2025/380).
6. Nature related Risks (link).
More news
Explore related insights and analysis